
Some of the business owners who could benefit most from a Health Spending Account are the ones least likely to have one: the incorporated solo owner, the couple running a business together, or the company with a single employee.
These owners rarely have a group benefit plan and often don't realize they can pay for health expenses through their corporation instead of out of their own pocket.
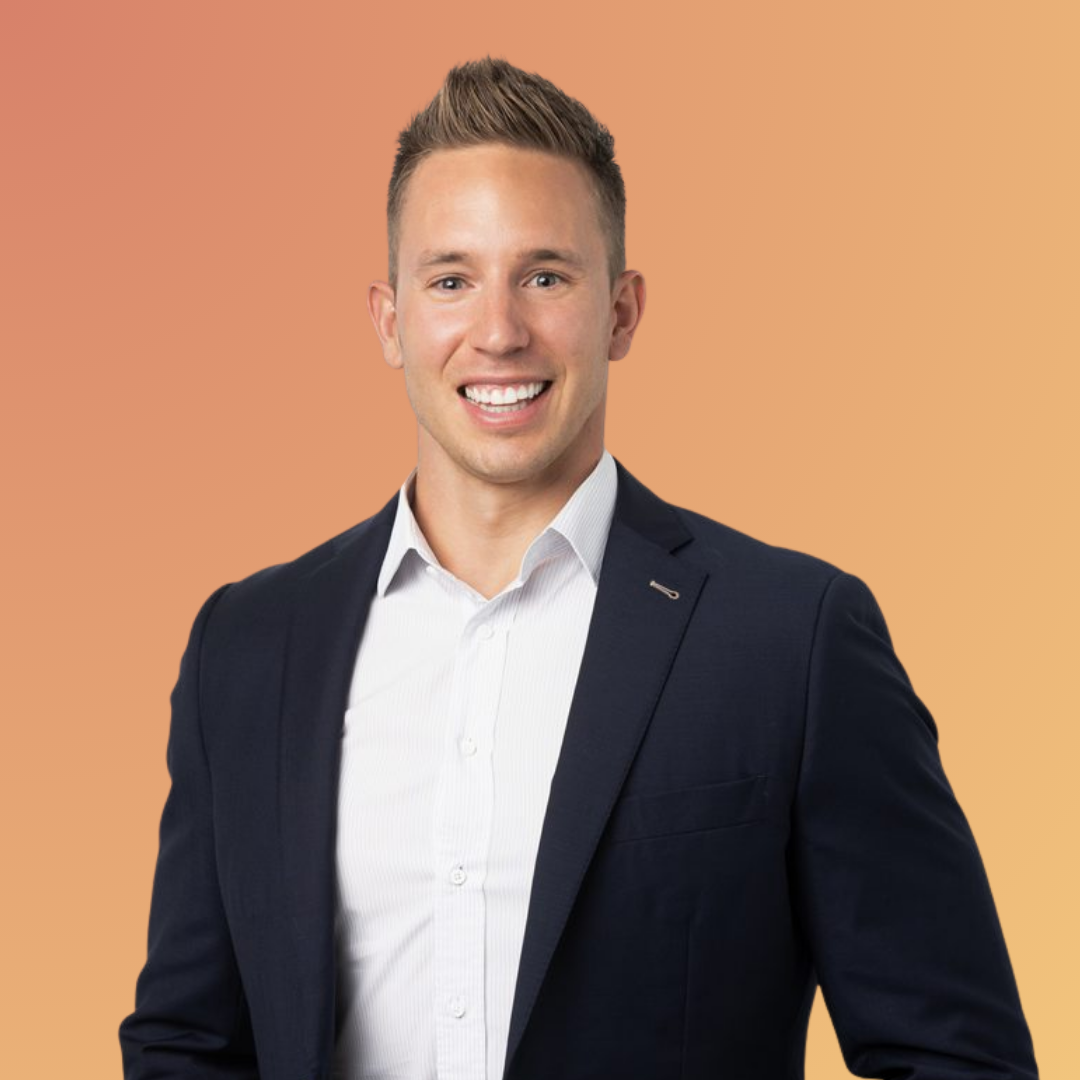
Guillaume Girard is the financial planner behind Girard Wealth. His background is in institutional wealth management, where he spent years working with data, but he always knew he wanted to run his own firm and work with people one-on-one. Today he focuses on incorporated business owners, both those building wealth and those heading into retirement.
For Guillaume, the numbers are only part of the job.
"It sounds cliché, but it's ultimately your well-being, and using money to improve your well-being," he said. The goal isn't just to accumulate wealth; it's to have a great life and use money to get there.”
Serving clients completely is what led him to myHSA. Before connecting with the team, Guillaume hadn't heard of Health Spending Accounts at all. While looking for ways to serve his business-owner clients better, he came across myHSA and reached out. Kyle Welsh, Head of Sales at myHSA, walked him through what an HSA is, who needs one, and who it suits best, and then trained him on the platform. Kyle even joined Guillaume's podcast to share that knowledge with business owners directly.
The Solution
Many of Guillaume's clients run one-person corporations, sometimes with a spouse involved in the business or a single employee. These owners usually have no benefit plan at all, which makes an HSA an easy fit. Instead of paying for health expenses with personal after-tax dollars, they can run them through the corporation.
He has also noticed that the barrier is often awareness, not access. Many people simply don't know everything an HSA can cover. When the benefit is tied to the things clients already care about, it becomes real to them.
That ties back to his planning approach. With an HSA in place, Guillaume can build health spending into a client's budget, so they stop skipping the things that keep them healthy. A massage or appointment they might have put off becomes something they plan for and actually use.
Built for Advisors
For an advisor who doesn't have a background in group benefits, getting started could have been a hurdle. Guillaume found the opposite. Between Kyle's training and the resources in the advisor portal, onboarding was simple and the platform was easy to use from day one.
"Right from the get-go, I just felt like you wanted us to succeed," he said, describing myHSA as user-friendly, very reachable, and advisor-friendly.
His clients feel the same way. Guillaume says their feedback has been very positive: they find the platform intuitive, they love the app, and they're often surprised by how much is covered. He regularly shares myHSA's eligible expense resources, so clients know exactly what they can use their account for.
As his practice grows, Guillaume knows the options will grow with it. Beyond the HSA, myHSA offers flex plans and myASO for clients whose needs become more complex.
The Takeaway
For financial planners who serve business owners, a Health Spending Account isn't an add-on, it's part of a complete plan. For Guillaume, it fits naturally into his approach: using money to support well-being, and making sure clients get the most out of every corporate dollar.
His advice to other advisors is simple.
"First of all, you've got nothing to lose, and everything to gain, for you and your clients," he said, "If you're servicing business owners in Canada, and you're a financial planner who's trying to add all the services around the financial plan, this is a no-brainer."
And because clients only pay for what they use, there's no downside to having it in place.
"The least you can do is introduce it to them and set it up for them," Guillaume said. "It doesn't hurt to have it there available. There's only positive things to gain."
That idea of making benefits tangible is shaping what's next at myHSA. In 2027, myASO will introduce pre-built plan bundles for needs like fertility planning, weight management, executive benefits, Indigenous solutions, and more. Advisors can pick up a ready-made plan and customize it from there, instead of building one from scratch.
myHSA Academy is also on the way: a self-paced learning hub where advisors like Guillaume can learn the platform at their own speed, revisit topics anytime, and earn Continuous Education credits along the way.
For advisors like Guillaume, it all points to the same goal: making it easier to add real value around the financial plan, and to help clients use their benefits to build the life they want.